Batch the same kind of work
I kept calls together in one block, with planning and paperwork in blocks of their own. Switching between kinds of work drains you more than the work itself.
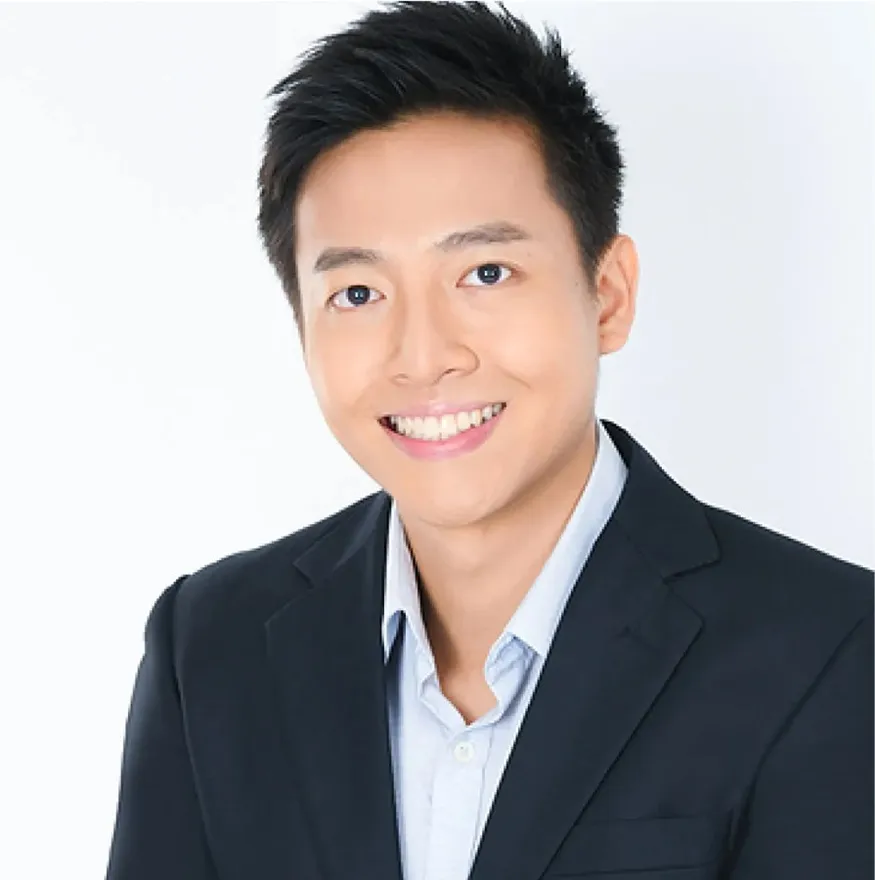
Leo started as a student financial adviser in 2016, alongside an Engineering degree at NUS, and qualified for MDRT four years in a row before he graduated. He went full-time in 2020. Since 2025 he has spent less time finding new clients and more time training new advisers through FINternship, a MoneyBees programme.
Hi, I’m Leo.
I started as a financial adviser in August 2016, a few months after national service, around the time I started an Engineering degree at NUS. For the next four years I did both. I went full-time when I graduated in 2020, so I’ve now been doing this for ten years.
I wasn’t an obvious fit. I had good A-level results and a plan that looked nothing like this one: finish engineering, do an MBA, then get a well-paid finance job. I was also an introvert with a stammer and a small circle of friends. Financial advisory was supposed to be something I tried on the side while I studied.
It went better than I expected. In 2017, my first full year, I qualified for the Million Dollar Round Table (MDRT). I qualified again every year until I graduated, so that’s four years in a row as a full-time student. I’ve since made MDRT five times and the Court of the Table three times, and served over 1,000 clients. Almost all of them were strangers when we first met.
None of it came easily. There were late nights after lectures, a slow start, a lot of rejection and some months when I earned very little. This book covers those parts as much as the good ones, because that’s what I wanted to know when I was 21 and nobody told me.
You might be reading this because you want more than a 9-to-5, and you’re also careful. Most new businesses fail, and you don’t want to lose years or savings finding out. I think that caution is a strength, so keep it while you read. The book is in five parts: my story, the business behind the job, whether it suits you, the inner game, and why starting as a student makes sense.
If you’re an undergraduate, an NSman, a fresh grad or just curious what this job is like when you do it part-time, I wrote this for you.
“Some weeks it felt like climbing a cliff with no rope.
A friend got me interested in personal finance in December 2015, right after I finished NS. He has since left the industry, but I still give him the credit for opening the door. I wanted to see more, so I signed up for a personal finance internship.
It started in May 2016 and ran for a few months. I learnt a lot about money, and even more about myself. The work suited me. It was hard, which I enjoyed, and I could see what a good plan did for the people we sat with. By the end I knew I wanted to keep going, so in August 2016 I joined as a student adviser.
That was around the time I started Engineering at NUS, on the Global Engineering Programme, a scholarship that squeezes four years of study into three. I was learning personal finance, learning the job and carrying an overloaded engineering timetable at once, and every part of it was new. Some weeks it felt like climbing a cliff with no rope. Slowly I found my footing in both, and the pressure started to feel like part of the fun.
Most people think this job is selling insurance. The real work is helping people and businesses make good decisions about their money. To do that well you need to know the markets, the products and the rules. You also need to know the client: what they want, and what they’re afraid of.
The work covers retirement planning, wealth management, insurance and investments. It takes analytical thinking and people skills in roughly equal measure.
More people are planning their finances, and the products keep getting more complicated, so demand for good advisers has grown steadily. Fintech, robo-advisers and AI are changing how advice gets delivered. They let an adviser reach more people and tailor advice faster.
They don’t replace the adviser, though. People still want someone who knows their situation, picks up the phone and explains things in plain language, and I expect that to stay true for a long time.
I’ve always found personal finance interesting. A bit of planning in your twenties decides whether you can buy a home, pay for your kids’ education or retire comfortably, and I liked that.
I also liked being useful to someone at those moments. Helping a client actually reach one of those goals still feels good every time.
And I wanted a job that would keep me learning. Markets change, products change and the rules change, so you can’t coast.
“Once I was actually doing the job, the stigma turned out to be smaller than I’d feared.
The internship got me interested. It didn’t get rid of my doubts.
The first doubt was the stigma. I knew how people saw financial advisers, as salespeople pushing insurance on friends who didn’t want it, and I didn’t want to be that guy.
The second was money. With no basic salary and everything on commission, I was nervous about the uncertainty, especially since my A-level results meant I had other options.
I treated it as a low-risk bet. Reading about the career cost me nothing, and if I tried it and hated it, I could walk away. I had little to lose and plenty to gain: some income while studying, a real understanding of personal finance, and work experience most of my classmates didn’t have.
The flexibility mattered just as much. There were no fixed hours, so I could book client meetings around lectures and exams. I liked running my own schedule. It suited the entrepreneur in me.
Once I was actually doing the job, the stigma turned out to be smaller than I’d feared. Most of my time went into teaching friends and clients about personal finance and helping them protect what they had. Seeing that settled my fears, and I started to really enjoy the work.
“I had two to three hours a day for this, so I couldn’t afford to waste any of them.
My weekdays belonged to lectures, tutorials and assignments. The Global Engineering Programme meant an overloaded timetable every semester, so I never had a whole free day. The business got two to three hours on weekday evenings, and I batched client meetings on weekends.
There was no virtual assistant back then and no mentor, so I wrote my own scripts and built my own slides from nothing. Every meeting was in person and every form was on paper. Admin took far longer than it does today. I still graduated with honours.
The lack of time is what made me good at this. With so few hours, I couldn’t waste any of them, and that pressure turned into habits.
Those first years were hard. On a normal day I had assignments, exams, client meetings, market research and policy reviews to fit in. I made myself one rule: go back to the office every day to make calls, even if only for an hour. After a while it stopped being a rule and became a habit.
The learning curve was steep and I had to adapt fast. I made a lot of mistakes, and I had a slow start. Each mistake taught me something, mostly about managing my time and sticking with things.
Commission work was its own lesson: some months paid well, then a few in a row paid almost nothing. Living through that taught me to budget and plan ahead, and to keep going in the lean months.
Everyone gets the same 24 hours. What separates people is how they spend them, and there are more pockets in a day than you think. Anyone who served NS knows “rush to wait, wait to rush”. The bus ride, the gap between lectures and the twenty minutes before dinner add up.
Four habits got the most out of my two hours.
I kept calls together in one block, with planning and paperwork in blocks of their own. Switching between kinds of work drains you more than the work itself.
Most of my results came from a small part of my work: meeting clients and following up. Admin and polishing slides could wait, or go to someone else.
Once I could, I passed scheduling, emails and paperwork to assistants, so my own hours went into the conversations only I could have.
I asked of every task: does this need to happen at all? Plenty of meetings and over-thinking didn’t.
If this career is a priority, you’ll find the time, the same way you find time for anything else you care about.
“Clients don’t want someone who talks at them. They want someone who listens.
Picture an introverted engineering student with a stammer and few friends, in a job where you meet new people every week. Most people would have told me to choose something else, and some probably did.
When I started, I knew nothing about sales. Building a pipeline, handling rejection and giving a decent presentation were all things I had to learn from zero, and a word like prospecting meant nothing to me. Attitude is what carried me. I stayed coachable, kept an open mind and showed up wanting to learn, because once you think you know it all, you stop getting better.
After more than 1,000 clients, I can tell you that very few of them wanted someone to talk at them. They wanted someone who understood what they were afraid of, listened without judging, asked good questions and gave advice they could trust.
Think about the last time you felt heard. It was probably with someone who let you finish your sentences. Your clients are the same.
My introversion turned out to be an advantage. These are the reasons I’ve seen it work, for me and for the quiet advisers I’ve trained.
While a talker plans their next line, you notice the hesitation and the real worry under the first question.
When you do speak, it sounds considered, and clients can tell it isn’t a rehearsed pitch.
Fifty people who trust you completely are worth more in this job than five hundred acquaintances.
Some of my best meetings turned in a silence, right after a hard question, while the client thought it through.
My business never depended on being good at parties. It depended on a way of finding clients that worked on days I didn’t feel sociable.
You don’t have to be a natural. We have scripts, frameworks and a step-by-step process, and a new adviser who follows them and stays coachable does better than a charmer who wings it. My stammer improved because the job made me practise speaking every week. If you want more practice, Toastmasters or a church or hall group gives you that too.
“There was no secret formula. It came from hard work, not giving up, and referrals.
Rejection is the first wall most new advisers hit, and I was no exception. It comes with sales, and some people say no bluntly. You can’t take it personally.
When someone turns you down, they’re turning down the offer in front of them that day. It says nothing about you as a person. Each no shows you something to change before you talk to the next person. I worked out early that I’d hear a lot of nos before each yes. It’s a numbers game, and every no gets you closer to the next yes.
Like most newcomers, I struggled to find good leads. Building a client base from nothing is slow, and it takes steady effort and some creativity. I got through it by doing more: more calls, more conversations, and plenty of strangers. My friends ran out within months, so I had to learn to win the trust of people who had never heard of me.
The good news is that it gets easier. As your client base grows, happy clients start sending people your way. Over time, referrals became my main way of finding new clients.
In 2017, still a student, I hit my first big milestone: MDRT. If you haven’t heard of it, the Million Dollar Round Table is an international association of top financial professionals, and you have to qualify again every year.
Qualifying more than once gave me confidence, and it reassured my clients. I was new to the industry, and MDRT showed that a lot of people trusted me enough to buy from me and refer me. It did more for my reputation than anything I could have said about myself.
The longer I did the job, the more the stigma looked like a misunderstanding. What I offered people was a plan for when things go wrong, built around what each of them needed. Once I saw the job that way, I approached clients differently, and rejection stopped feeling like a verdict on me.
I don’t only work with wealthy people. Most of my clients are ordinary people living ordinary lives, not tycoons or rich retirees, and what they want from me is sound advice and a plan they can stick to. I believe everyone deserves good financial advice, whatever they earn, so my aim is the same with each of them: leave them better off than before we met.
These days most of my time goes into serving existing clients, plus the referrals that come my way. Clients often become friends, and friends often become clients. Those relationships are how my practice grew, and the job is more enjoyable for it.
“The worst case was that I’d walk away knowing how money works and how to talk to people.
Before we talk about this career, look at what it takes to start a normal business.
A business partner of mine once got excited about opening a Ya Kun Kaya Toast franchise. His friend owned several profitable outlets, so it looked like a sure bet. Then he saw the numbers: over $200,000 to start, plus a royalty of nearly 10% of revenue every year. The dream faded quickly.
I once looked at starting a GP clinic with a friend. It needed $650,000 to open. Even at $1 million in revenue a year, the profit after rent and salaries came to about $10,000 a month, so breaking even would take five to six years, and only if everything went right.
Sometimes the risk isn’t only money. I once considered buying a pain clinic in a well-known shopping centre. It made $500,000 a year in revenue, but the owner took home $80,000, and he wanted $500,000 for it. He also ran the front desk, the operations, the sales and the treatments himself. If I’d bought it, I wouldn’t have owned a business. I’d have bought myself an expensive, stressful job.
That’s the entrepreneur’s problem in a sentence: the way to freedom is often blocked by the money you need, the fear of failing, and the risk of building yourself a new cage.
Think about why McDonald’s, Old Chang Kee or Ya Kun grew so far. Their franchise system lets a new owner skip the hard part. The branding, the marketing plan and the operations already exist, and the owner runs a model that has already worked.
Financial advisory works the same way. You don’t build a financial company, design insurance or investment products, or spend millions on research. The company has spent decades building the products, the brand, the claims team and the systems, and you start with a major insurer’s name behind you from day one.
The difference is the cost. There’s no $200,000 fee and no royalty, and nothing to rent or stock before your first client. When I started at 21, I didn’t realise I was starting a business, because it came without the usual cost in money or time. The worst case was that I’d walk away knowing how money works and how to talk to people.
Your job is to drive the car, not build it. A traditional franchise doesn’t come with a mentor, and this one does: the scripts, templates and marketing material I spent years building are yours on day one, so you don’t have to repeat my mistakes.
Here are the two ways this can go.
You put in the work and it pays off. You build a career with a good income and control of your own time, a client base that keeps growing, and the chance to lead and mentor other people.
You decide it isn’t for you. You still leave knowing more about money than most of your friends, with real sales and communication skills, and with the discipline that comes from doing hard things.
A bet where the bad outcome still leaves you better off is rare. The real risk is never finding out.
“Your real hourly rate is what a client is worth over the years, divided by the hours it took to win and serve them.
Flexible work can quietly turn into more hours for less money. Before you choose a business, do the maths on your time. Your real hourly rate is what a client is worth to you over the years, divided by all the hours it took to win them and look after them.
During my reservist, I talked to an interior designer. He was good at sales and loved his work, but the business model was wearing him down. He’d closed a project nine months earlier, and the client still didn’t have their keys, so he was looking at about a year before he collected his full commission.
So we worked it out. Closing one sale took him about 25 hours: preparation, three meetings and the proposal. Managing the project afterwards took another 50 hours of coordinating clients and contractors. That’s 75 hours of work for one sale, paid a year later, and the same client wouldn’t renovate again for five to ten years.
Winning a new client takes me about 15 hours: six of calling, six of preparation and three of meetings. There are no 50 hours of project management afterwards. Once a plan is in place, the company does the delivery. Fund managers grow the money, and the claims team pays out.
The client doesn’t disappear either. They keep their plans for years, add new ones as life changes, and refer friends. So one client is worth far more over time than the first sale, while the hours to win them stay small.
Once you see that, your choices change. It becomes worth paying someone for low-value tasks so you can spend your hours on clients. Following up and serving people well becomes the best investment you can make.
Look at the businesses you use every day. Apple sells you a phone, then iCloud, then the next phone. Netflix and Adobe charge every month. Starbucks turns one coffee into a daily habit. Each of them values a customer by everything that person buys over the years, which is why they can spend so much on keeping you.
I learnt this the hard way with my digital marketing agency. Cheaper freelancers kept appearing, and while some clients stayed for years, most left after six to twelve months. I was always replacing the ones I’d lost.
Financial advisory works the other way round. A retirement plan isn’t something people cancel after six months, so most clients stay for decades. They come back when they marry, buy a home, have children or get promoted, because each of those creates a new need. You’re planting an orchard, and the trees keep bearing fruit for years.
Most service businesses hit a ceiling. The interior designer could only handle five projects at a time, so a big sales month meant less time for selling the next month. With my agency, more clients meant more staff, more costs and more problems.
An adviser starts with a team the company pays for: underwriters, fund managers, customer service and product managers. They do the slow, complicated work behind the scenes, so you can keep finding new clients month after month without running into a wall. That’s why, with over 1,000 clients, I only need two virtual assistants for the admin. It scales more like software than like a service business.
“A 9-to-5 pays you to do a function. This career pays you to learn how to build.
A 9-to-5 pays you to do a function. This career pays you to learn how to build, and the business sense behind the four other companies I’ve started came from what I learnt here. Even if you decide this isn’t your long-term path, the skills below stay with you for good.
Selling isn’t pushing. Every founder sells a vision to investors, a product to customers and a mission to a team. You’ll learn what makes people decide, how to bring people to you instead of chasing them, and how to explain value so clearly that the decision is easy.
You’ll learn to ask the right questions and hear the answer, and to build trust with people of every background. It’s the base of every team you’ll ever lead and every deal you’ll ever close.
School doesn’t teach personal finance, and most people learn it through expensive mistakes. Here you get paid to learn how money is protected, managed and grown, for your clients and for yourself.
Clients trust you with their financial future. That responsibility pushes you to hold yourself to high ethical standards, and the habit lasts.
It’s close to running your own company. You’ll plan your pipeline, manage your time, read your numbers and see your own weak spots clearly.
Pushing through the early months and staying steady through the ups and downs teaches you to keep going when it would be easier to stop.
Push through the first few years, and this career pays you back in time.
“Most jobs make you trade one of these for another.
When I looked at any job, I was looking for five things.
I wanted to do well at work and still have time for my family, my friends and my own interests. Because I set my own schedule and work at my own pace, this job gives me room for all of them. As a student, my days went to lectures, and the business got my evenings. A corporate job wouldn’t have let me shape my week like that.
Everyone wants their work noticed, and I’m no different. In this job, recognition comes from awards and from clients. I’ve been an MDRT member and I’ve been invited to give talks about how I started. Clients have also said a lot of kind things over the years, and those keep me going on the hard weeks.
For me, fulfillment comes from the difference I make for people. Schools don’t teach money, so most people work it out alone. I help clients protect their families, build savings and review what they already hold, so they stop guessing. That matters more to me than the money.
Income matters in any job. In this one, what I earn follows the effort I put in, there’s no fixed ceiling, and you can grow into a manager or director with a team of your own. It let me reach my financial goals much earlier than I had planned, and it was a big reason I went full-time.
Plenty of people worry about job security right now. Financial advisory has held up through good years and bad, because people always need advice and a plan. That gave me a kind of security I didn’t see in many other jobs.
Most jobs make you trade one of these for another. A well-paid job usually costs you your evenings, and a job with good hours usually pays less. Few jobs come with much recognition, and COVID-19 showed in 2020 how quickly job security can disappear. This job gave me all five.
So I went full-time in 2020, when I graduated. Since then there have been overseas trips, company retreats, award ceremonies and talks about my results. That’s why I ask students: why wait until you graduate to start?
“Did you put in the work today, whatever happened yesterday?
We don’t look for the most experienced, the best connected or the most charming people. Experience can be gained, connections can be built and charisma can be learnt. These four traits are much harder to change, and they predict who does well better than any qualification.
Most people have an idea, think about it for days, ask everyone’s opinion, wait for the perfect moment and then never start. The people who do well have an idea, act on it within a day, and adjust as they go.
Two recruits joined in the same month. The first spent three weeks on research: the perfect CRM, the best cold-calling scripts, a pile of sales videos. He made 50 calls in his first month and set 2 appointments. The second said, “I don’t know what I’m doing, but let me start calling,” used the script we gave him, got rejected, and adjusted. He made 500 calls and set 15 appointments.
I try to work the same way. One Saturday morning I saw another team post a financial calculator that was getting a lot of attention. By Saturday afternoon I’d built our own version in about four hours, with ChatGPT writing the code. The team had it on Sunday, and on Monday three advisers used it to close cases. Spending two weeks perfecting it would have cost us the moment.
Most people learn the basics and then coast. The ones who do well review every meeting: what could I have done better, what put them off, what worked and how do I repeat it. Every week they look at their numbers and ask how to improve them a little.
One new adviser had ten appointments in his second month and closed none. He could have blamed the leads. Instead he asked us to review a recording of his next meeting. He was talking 80% of the time and asking questions 20% of the time, so clients felt sold to. We gave him a set of questions to ask before any pitch. The next month, with the same kind of leads, he had twelve appointments and closed five.
Take feedback without getting defensive, ask for it before anyone offers, try new approaches and own the result.
This career will knock you down, repeatedly. In your first weeks, most people will hang up on you, appointments will cancel, and a client who loved your plan will say they need to think about it. Low performers take days off to recover. High performers expect the knocks and keep going.
I played competitive tennis before this career, and it taught me how to handle results. After a win, you don’t celebrate too long, because there’s another match tomorrow. A loss isn’t a reason to sulk: you work out what went wrong and train. The only question that matters is whether you put in the work today, whatever happened yesterday.
So we look for steady people. A bad month means checking the activity, the pitch and the leads, then carrying on. A great month means asking how to repeat it, not deciding you’ve made it. The calls happen on the days you feel like it and on the days you don’t.
Some people say they can’t run ads because they don’t know the software, or can’t call because their script isn’t perfect. Others watch three videos that night, use the basic script and improve it, or study for two hours every evening until they’re confident.
When one adviser hit an objection he couldn’t answer, he didn’t wait two weeks for the next training. He searched our library, asked the AI assistant, watched recordings of past meetings and then messaged his mentor. He had his answer in twenty minutes and closed the case the next day.
Another adviser wanted to reach senior executives, but our ads weren’t bringing them in. He didn’t give up on them. He suggested a guide written for executives and offered to write it if we designed it, and we built it in 48 hours. His leads cost more, and they closed about three times as often as the ones he’d had before.
Yes, with intent. Start with small promises you keep, like ten calls today no matter what. Find a mentor who challenges you instead of one who only agrees with you. Track your daily activity. Before asking for help, spend fifteen minutes trying to solve it yourself.
Ask yourself honestly:
When you have an idea, do you act within a day or two, or think about it for weeks?
When something fails, do you blame the circumstances, or ask what you can do better next time?
On days you don’t feel motivated, do you still do the minimum you promised yourself?
When you hit a problem, do you wait for someone to solve it, or try to figure it out first?
Four yeses means we should talk. With one or two noes, you can still build the missing traits, as long as you work on them on purpose.
“Nobody has ever asked to see my office before becoming a client.
These four beliefs talk more people out of this career than anything else. Each one has a grain of truth, and each one falls apart when you look closely.
Almost all of my clients were strangers when we met. I reached MDRT five times and served over 1,000 clients without relying on friends and family.
Friends can still be a good start. They already trust your character, so they’re often your first clients, and they help you practise. If you believe your advice can help them, you should offer it, because otherwise someone else will, and that person may not be around in two years. Friends do run out, though, so a business built only on them has a short life.
That’s why new advisers on our team start with more than one source of clients: their own network, cold prospecting methods we teach, and leads we generate. Our campaigns bring in people who have signed up for a guide or a free tool, so they’ve already raised a hand. Appointment setters and an AI assistant on WhatsApp reply to them, book them in and send reminders, so you spend your hours in the meetings.
As a student, your day looks something like this: eight hours of school, eight hours of sleep, four hours for friends and rest, and four hours for the business. Spending two of those on the way to an office and back makes no sense.
The work that brings in clients happens anywhere. You call and text from home, meet clients at a cafe or on Zoom, and follow up from your phone. I built my practice in coffee shops, on campus between classes and at home after lectures, and nobody has ever asked to see my office before becoming a client. They ask whether you understand their problem, whether you reply quickly, and whether they can trust you.
When you compare agencies, skip the question about the office. Ask these instead:
Our approved lead campaigns are partly subsidised, so you aren’t paying for every lead yourself.
Our assistants prepare policy summaries, submit claims, answer client questions and handle the paperwork.
Appointment setters and the AI assistant contact new leads and put the meeting in your calendar.
This number tells you more about the support than any brochure.
Fun events, people your age and a sense of belonging are all good things. They don’t build your skill, though, and skill is what keeps you in this job.
Sales is value crossing a bridge of trust. Friends already trust you, so they’ll buy on less proof, while a stranger needs to see that you’re good at this. You’d pick a heart surgeon for his skill, and his being a friend wouldn’t come into it. Advisers who only learn to sell to people who already like them struggle when the friends run out, because strangers ask for much more. Learn to win strangers first, and your friends will be easy whenever you want.
So split what you’re looking for into two. For community, fun and practice speaking, join a real community: for me that’s church and a group that hangs out every Saturday with no agenda. For work, go where you’ll build the skill, the way a surgeon goes to surgery school.
I once spoke to an adviser who believed he needed to offer every company’s products to feel convinced he was recommending the best. After more than a year he was getting one appointment a week, sometimes none. Product range wasn’t his problem. He had nobody to present to.
Clients rarely choose an adviser for the length of a product list. They choose for trust, good service, quick replies and expertise they can feel. Conviction comes from knowing a smaller range inside out, seeing it work for real clients, and having a team behind you for claims, admin and service.
When you choose where to start, ask which place gives you a steady flow of people to talk to, training that turns meetings into clients, and the support to serve them well. Product range matters only once you have the first.
“The bigger your why, the easier it is to overcome the how.
What gets you out of bed in the morning, and what keeps you going when a week goes badly? Whatever the answer is for you, that’s what I mean by your why.
John C. Maxwell puts it simply: “Find your why and you’ll find your way.” In a job with as many ups and downs as this one, your why does a lot of the work.
Everyone’s why is different. Some people want to help others get on top of their money. Some want to prove something to themselves, and some want to build wealth. What matters most is how strong it is. A strong why keeps you moving on the days you’d rather quit.
When I started, my why was ambition. I wanted to prove my worth and get ahead of my peers in a race that went well beyond grades. I chased big targets, and I measured myself by what I achieved.
That changed slowly as I got to know my clients’ lives. Helping people get stable, and teaching them how to protect their future, started to matter more to me than the targets. My why moved from me to the people I served.
Your why will change too. As you grow, it shifts with your values and your experiences. Finding it is more like peeling an onion than answering a question: you might start with one reason and end up with a better one.
Whatever yours is, it’s what keeps you going when things get hard. Spend some time on it. Look at what you value, and check that what you do every day matches it. The bigger your why, the easier it is to overcome the how.
“What’s work success worth if there’s no one to share it with?
People say success isn’t all it’s cracked up to be. I used to think that was something people said when they hadn’t made it. Then I hit my dream income, went further in my career than I’d imagined and started a digital marketing business on the side, and I began to see their point. On paper I’d made it, but inside I felt empty, and I couldn’t explain why.
The hustle left room for nothing else. My friends kept losing out to work. Life was work, sleep and repeat, and I was losing what makes life worth living: connection, joy and purpose.
It came to a head in 2020. I was about to graduate and I had almost no close friends. What’s work success worth if there’s no one to share it with? A friend had invited me to church many times, and I finally went with them, which turned out to change a lot for me.
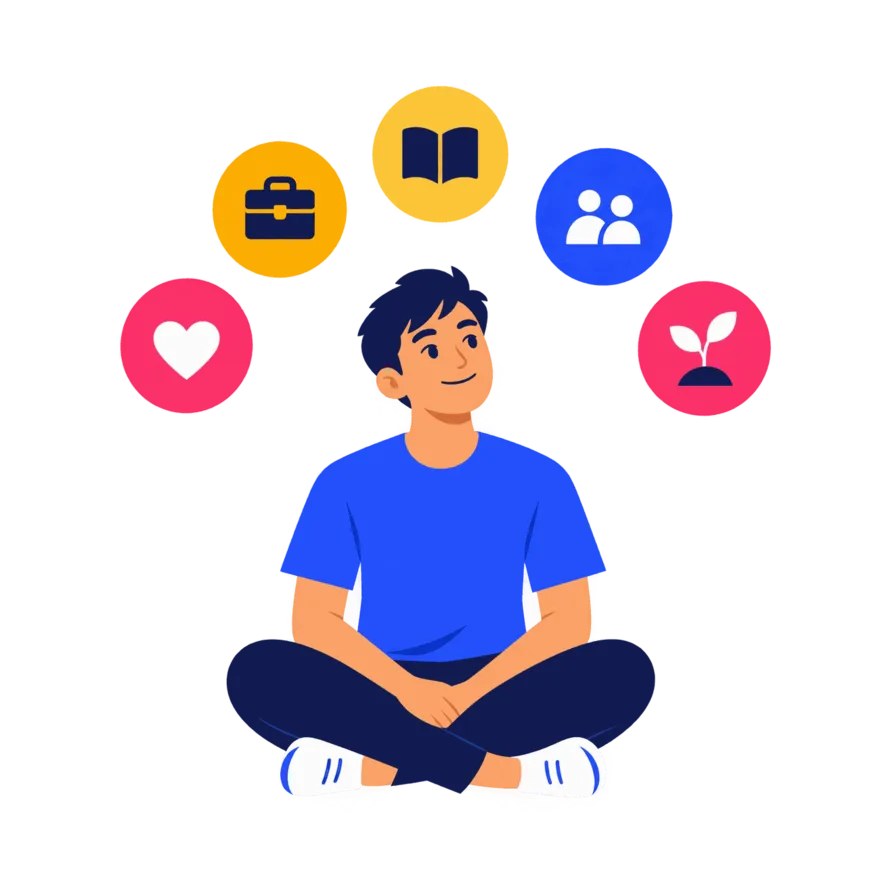
That day I heard an idea that stuck with me. Living well means growing in five areas of life. Career and finance was the first, and I knew that one well. The others were health (physical and mental), learning and personal growth, friendships, and spiritual growth.
I’d put almost everything into the first one and neglected the rest. That’s probably why I felt empty despite everything I’d achieved.
Since then I’ve worked on all five. My life feels fuller for it, and I’m happier now than I was when work was all I had. Success for me today mostly means feeling content.
Anyone starting a new career should ask: what’s my motivation? Money, recognition, fame or just wanting to be successful are all common answers. In this job those motives can get you results fast. The happiness they bring doesn’t last, though, and you end up wanting more.
Before I found my faith I felt lost, lonely and hollow. My achievements looked good from the outside and didn’t fill the gap. At church I found a joy that had nothing to do with results. I learnt to care about other people without expecting anything back, and that gave my career the purpose it had been missing.
It’s easy to tie your happiness to your results. The harder you chase it that way, the further away it gets. I’ve watched colleagues fixed on their targets and income goals hit them and then burn out, frustrated. The advisers who come in wanting to help people enjoy the job more and last longer. Every client you help, and every money worry you take off someone’s plate, gives the work meaning.
This career is a marathon, run at your own pace. What satisfies me most is knowing my work helps other people, and since 2025 I’ve spent much of my time training new advisers so they don’t have to learn it all the hard way like I did.
“For me, the question is less “why?” and more “why not?”
You might be asking: why become a student adviser, and what’s in it for me? Fair questions. The role has its challenges. It’s also one of the best ways I know to grow early, personally and professionally. For me, the question is less “why?” and more “why not?”
You’ll learn to lead, communicate and solve problems, and to connect with all kinds of people. Every career needs those skills.
You’ll learn financial planning, insurance and investing years before most of your friends do.
Employers notice when a full-time student has taken on real responsibility, worked independently and juggled several things at once.
You’ll meet professionals who can lead you to internships, mentors and job offers before you graduate.
Helping someone sort out their money and seeing the difference it makes feels good in a way most student jobs don’t.
As a student, your main job is to learn and try things. Being a student adviser lets you see the industry from the inside without committing to it. The pace is gentler than a full-time role, and if it isn’t for you, you move on when you graduate having lost very little. You add experience to your resume without closing any doors. You’ll miss some hangouts, the odd late movie and a few weekend lie-ins, and the time-management habits you build will help in every job after this one.
If all your money comes from one source, you’re more exposed than you think. This job can give you a second stream while you study, and later a career of its own.
The early stage is hard work. You have to build a client base, give good advice and look after people well. That effort is what pays for everything that comes later.
Part of what you earn is residual. When clients keep the plans they bought, you keep earning renewal commissions and bonuses on them in the years that follow, on top of anything new you do. Those stack year after year, so an adviser who keeps serving clients well builds an income that holds up even in a year when new sales are slow. By my third year, the income from my existing clients was higher than what many of my friends earned in their full-time jobs.
These days I don’t work for the next paycheck. That gave me room to invest in myself, take risks and try new things. As a student adviser, you can start building that earlier, alongside your studies, with less at stake.
The first few years take a lot of time, as in any career. Once you have a solid client base and steady income, the pace eases and the flexibility becomes obvious. Lawyers, doctors and auditors often work more than 50 hours a week. In this career you eventually set your own schedule, and to me, balance means giving career, family, friends and health each their share.
Fresh graduates often judge a job by its salary, and students pick part-time jobs by the hourly rate. What gets missed is the purpose behind the work. As advisers we have real influence over our clients’ decisions, and the industry pays well, which creates a temptation to put profit ahead of integrity. That’s why you need a firm moral compass, and why your clients’ interests have to come first. We’re educators and guides as much as advisers, and seeing the job that way is what keeps a career going.
“Nobody expects you to know all this on day one.
These are the questions I get most from students thinking about this career. Nobody expects you to know all this on day one.
In a salaried job, your pay is usually fixed, whatever you put in, and your hours are set by someone else. As an adviser you’re self-employed: your income follows your effort and results, and you decide your hours and your clients. Many corporate roles are cost centres, where the job is to avoid mistakes. This one is closer to running your own firm, and your security comes from a client base that keeps paying renewals, not from one employer.
No. Friends can be a good start, because they already trust you, and if you believe your advice can help them you should offer it. Almost all of my own clients were strangers, and our lead campaigns and appointment setters mean you won’t depend on your network.
There are four main ways, and we teach all of them. Cold calling works for disciplined people with a clear target audience and a script that names a real problem. Direct outreach on WhatsApp, Telegram, Instagram, LinkedIn and TikTok needs good follow-up habits. Catch-ups with your own network work when your intention to help is clear. Hobby and interest groups are slow, and the trust you build there lasts. On top of those, our campaigns bring in people who asked for help, and we lead with something useful, like a policy review or a calculator, before suggesting anything.
We teach a three-step reply: acknowledge, relate, and turn it around. You acknowledge that they’re clearly responsible with money, relate it to getting a second opinion from another doctor, and then offer to check their plans for blind spots. You’ll also learn to ask questions that make “no” the easy answer, like “Would you be against me sharing this with you?”, and to say “questions” instead of “concerns”.
As a student I gave it about two hours on weekday evenings and batched meetings on weekends. Roughly one in five appointments becomes a client, so two new clients a month means about ten appointments, and calling and texting to fill them takes a few hours a week. With appointment setters and an AI assistant doing some of that work, it takes less.
Your renewals keep coming from the clients who keep their plans, along with the bonuses on them. Every year of good work adds to that base, which is why a slow year doesn’t take you back to zero.
Yes. That’s what FINternship is for: ten days in December where you learn how markets work, practise speaking to a room and meet the people who do this for a living. The details are on the next page.
“My advice, if you’re thinking about becoming a financial adviser, is to take the leap.
Finding a career that fits you is hard. Mine came with challenges, worries and plenty of self-doubt. Every step forward taught me something, and I’m still growing because of it.
People misunderstand and undervalue this industry. In my experience it’s a place to grow as a person, to have a life outside work and to do work that means something. You get to teach people about money and help them build a stable future, and the job runs on relationships and trust.
We’re not trying to recruit hundreds of people. We’re looking for a handful who act fast, keep improving, show up when they don’t feel like it and figure things out. If that sounds like you, the systems, the leads and the mentoring are ready, and you won’t have to work it all out alone the way I did.
My advice, if you’re thinking about becoming a financial adviser, is to take the leap. Expect it to be hard, and let it make you stronger. Don’t let other people’s opinions decide this for you. Look at the career for what it really is.
Choose a career that fits who you are and what you care about. Then make the most of it.
Ten days in December. Learn to invest from people who manage millions, and practise owning the room when you speak.
by Leo Tan, Founder of MoneyBees. Read more at themoneybees.co
Junxiong-WFG Organisation is an authorised representative of AIA Financial Advisers Private Limited (Reg. No. 201715016G).
Information is correct as at 7 October 2026.
This ebook is not an official publication of AIA Financial Advisers Private Limited (Reg. No. 201715016G) (AIA FA). AIA FA disclaims all warranties of merchantability and fitness for purpose of the materials in this ebook. AIA FA makes no warranties or representations as to the results of the use of the materials in this ebook in terms of their correctness, accuracy and reliability. Nothing in this ebook should be regarded as an offer or solicitation to sell insurance products in any country to any person to whom it is unlawful to make such an invitation or solicitation in such a country.
Terms of Use. (1) All trademarks, service marks, trade names, product names, icons and logos of AIA FA are owned by AIA FA and may not be used without prior written permission from AIA FA. (2) All AIA products and AIA FA services referred to in this website (or linked thereto to the website) known as www.themoneybees.co (the “Agency Website”) are offered only in countries where such products and services may lawfully be offered by AIA Singapore and AIA FA respectively. (3) Neither the Agency Website nor the link to the products or services on AIA FA’s corporate website should be regarded as an offer to sell or a solicitation to buy any insurance product or other products of AIA Singapore or services of AIA FA. (4) No warranties regarding non-infringement of third party rights, security, accuracy, fitness for purpose, merchantability or freedom from computer viruses in the Agency Website or the AIA FA corporate website (linked thereto) are given by AIA FA.